Diamondback Energy’s $5 billion acquisition of Permian Basin holdings from Double Eagle is more than a large transaction—it is a clear signal that U.S. shale consolidation remains firmly in play. For traders watching $FANG, the deal creates a fresh company-specific catalyst while putting the Permian’s competitive landscape and the broader energy M&A cycle back in focus.
The headline number matters. The transaction ranks among the largest Permian Basin deals reported this period, giving Diamondback Energy a move with enough scale to command attention well beyond the two companies involved. The market’s next question is not whether consolidation exists, but how investors will judge the strategic weight of this acquisition.
A sizeable Permian statement
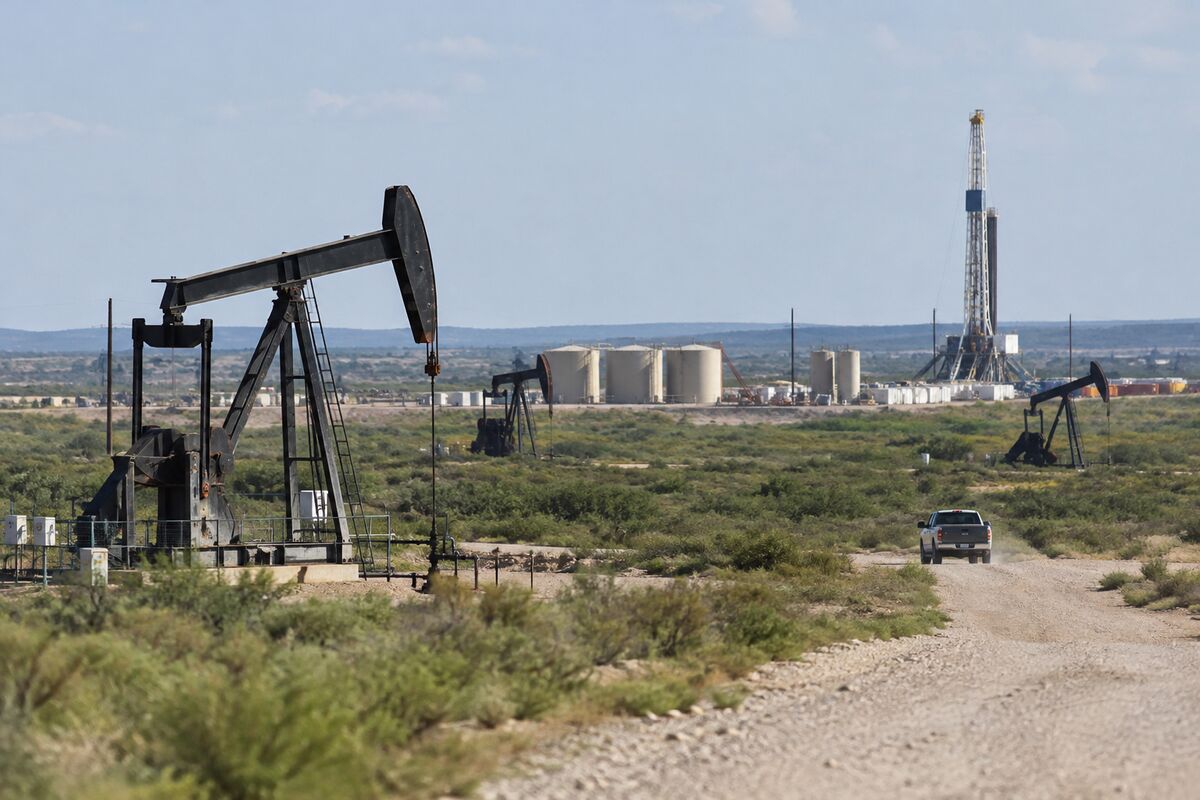
Diamondback Energy’s confirmed agreement to acquire the Double Eagle holdings places the Permian Basin at the center of the shale consolidation debate once again. The basin remains a critical arena for U.S. energy producers, and a $5 billion transaction suggests that high-quality or strategically relevant assets continue to attract serious corporate attention.
That does not automatically make the deal accretive, transformative or immediately beneficial for shareholders. Those judgments will depend on how the market evaluates the assets, the purchase price and Diamondback Energy’s broader operating strategy. Still, the scale alone makes this a significant corporate action and one traders are likely to use as a reference point when assessing future transactions.
As the reported announcement details confirm, Diamondback Energy has committed to a $5 billion deal for Permian holdings from Double Eagle. That straightforward fact carries a broader implication: major shale operators continue to see value in expanding their position in a basin where scale and acreage concentration can shape competitive standing.
Why the deal matters for FANG
For holders and traders tracking $FANG, the acquisition may become a near-term catalyst because it gives the market a concrete strategic development to analyze. The stock’s response could reflect more than the transaction itself. It may also reveal whether investors favor Diamondback Energy’s effort to strengthen its Permian footprint or remain cautious about the implications of a deal this large.
That distinction is important. A major acquisition can sharpen a company’s strategic profile, but it can also prompt closer scrutiny of execution. Traders may focus on whether the transaction is viewed as reinforcing Diamondback Energy’s position, changing its competitive trajectory or simply adding another large corporate commitment to an already active shale landscape.
A broader M&A signal
The Double Eagle transaction also sends a message to the wider energy sector. When one of the largest Permian deals reported this period comes from a major U.S. shale producer, other companies may face greater pressure to evaluate their own acreage positions and strategic alternatives. That could help sustain attention on energy-sector M&A sentiment, even without a wave of immediately announced transactions.
The contrarian read is that consolidation headlines do not guarantee a uniformly bullish response across the sector. Larger deals can intensify questions about valuation, integration and capital discipline. The more constructive interpretation is that Diamondback Energy’s move indicates strategic appetite remains present in U.S. shale, particularly in the Permian Basin.
For now, $FANG is the cleanest trading expression of that debate. Diamondback Energy’s $5 billion Double Eagle agreement gives investors a fresh event to assess and gives the broader market another data point in the continuing consolidation story.
Bull/Bear Verdict
Bull Case: The $5 billion Double Eagle acquisition could strengthen Diamondback Energy’s Permian position, provide a fresh catalyst for $FANG and reinforce constructive energy M&A sentiment.
Bear Case: The deal’s size could prompt greater scrutiny of Diamondback Energy’s execution and valuation, leaving $FANG exposed to a cautious market response despite the transaction’s strategic significance.