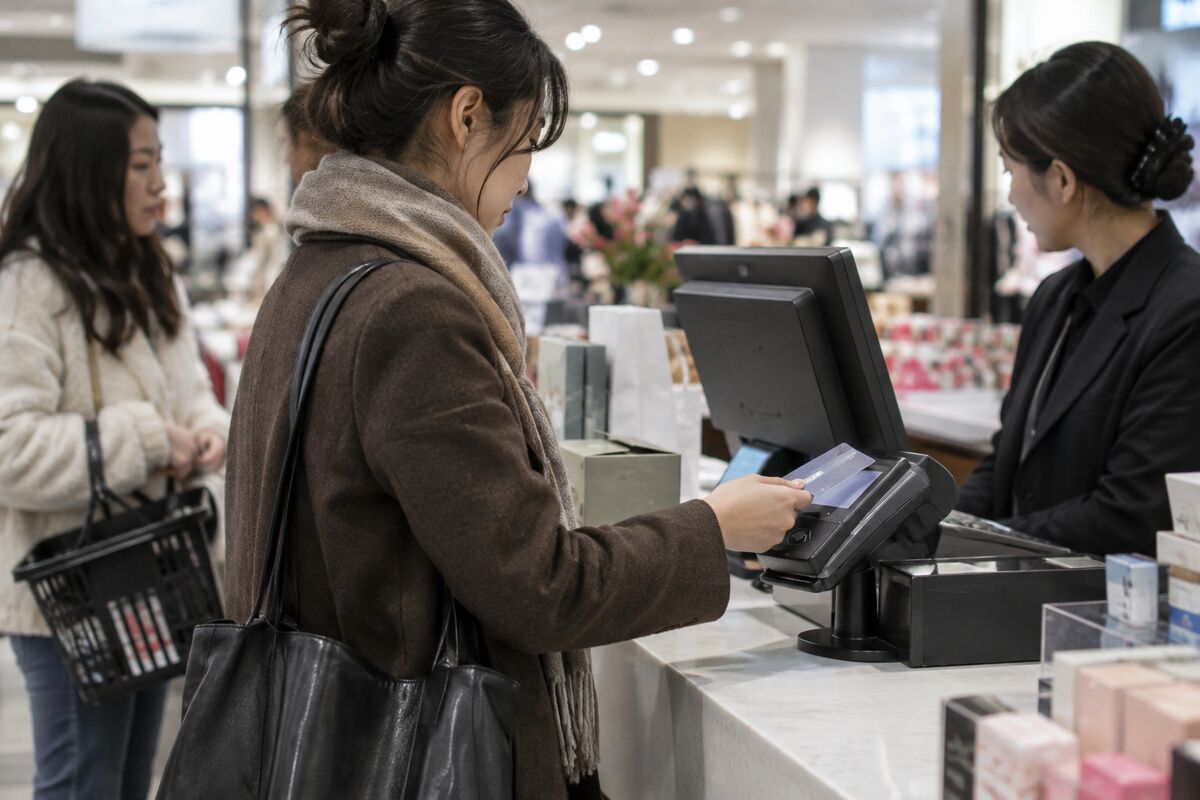
US consumers are still spending, but October’s retail-sales performance suggests that resilience is becoming more expensive to maintain. Growth slowed to its weakest pace in nearly a year, according to the CNBC/NRF Retail Monitor, turning a familiar strength of the economy into a potential warning signal.
That distinction matters for markets. The consumer has not stopped spending, yet elevated prices are placing increasing pressure on household purchasing power. For traders, the question is no longer simply whether Americans are buying—it is whether demand can remain firm while inflation persists and interest rates stay high.
The CNBC/NRF Retail Monitor report describes October retail-sales growth as the slowest in nearly a year. The result points to deceleration rather than an outright collapse: consumers continue to spend, but the pace is losing momentum.
Consumer resilience meets price pressure
Retail spending can remain positive even as households feel more constrained. Higher prices mean consumers may be spending more simply to maintain existing purchasing patterns, while having less flexibility for discretionary purchases. That creates a delicate backdrop for the US consumer sector.
The National Retail Federation’s data therefore carries significance beyond the monthly retail number. It indicates that consumer strength may be narrowing, with spending continuing but strain becoming more visible. That dynamic could matter most for consumer-discretionary companies, whose results are often more exposed to changes in household confidence and available income.
For those companies, slower retail growth may increase the importance of pricing, promotions and product mix. Persistent inflation can support sales values, but it can also pressure consumers and make demand more sensitive to price. The result could be a tougher operating environment even if headline spending remains positive.
Why traders may focus on GDP implications
Consumer spending is a central part of economic activity, so a sustained slowdown in retail-sales growth could point to weaker GDP momentum ahead. October’s result does not establish that outcome by itself, but it gives markets another reason to test the durability of the US expansion.
The interest-rate backdrop makes the signal more consequential. Higher rates can weigh on household budgets and financing conditions, while persistent price pressures limit the relief consumers receive from any moderation in spending. Together, those forces create a difficult policy and market combination: demand may be cooling before inflation has fully eased.
The stagflation question
That is where the stagflationary concern enters the discussion. A combination of slowing demand, continued price pressure and higher interest rates would be particularly challenging for consumer-facing businesses and the broader economy. The October reading does not prove that such a combination is developing, but it highlights the conditions traders are watching.
The market takeaway is measured rather than dramatic. Consumers are still spending, which provides a degree of support for economic activity. But the nearly one-year low in retail-sales growth suggests that support may be weakening at the margin. If future data confirm the slowdown, consumer-discretionary stocks and GDP expectations could face greater pressure. If spending reaccelerates, the October reading may instead prove to be a temporary loss of momentum.
Bull/Bear Verdict
Bull Case: Continued consumer spending, despite elevated prices, may indicate that US demand retains enough resilience to support economic activity and limit near-term pressure on consumer-discretionary companies.
Bear Case: Retail-sales growth at its slowest pace in nearly a year, combined with persistent inflation and higher rates, could signal weaker GDP momentum and raise the risk of a stagflationary environment.