JetBlue is asking investors and creditors to look beyond its low-cost-carrier label. Chief Executive Officer Joanna Geraghty is defending a premium-service strategy designed to improve the airline’s path back to positive earnings, even as creditor concerns keep balance-sheet pressure in focus.
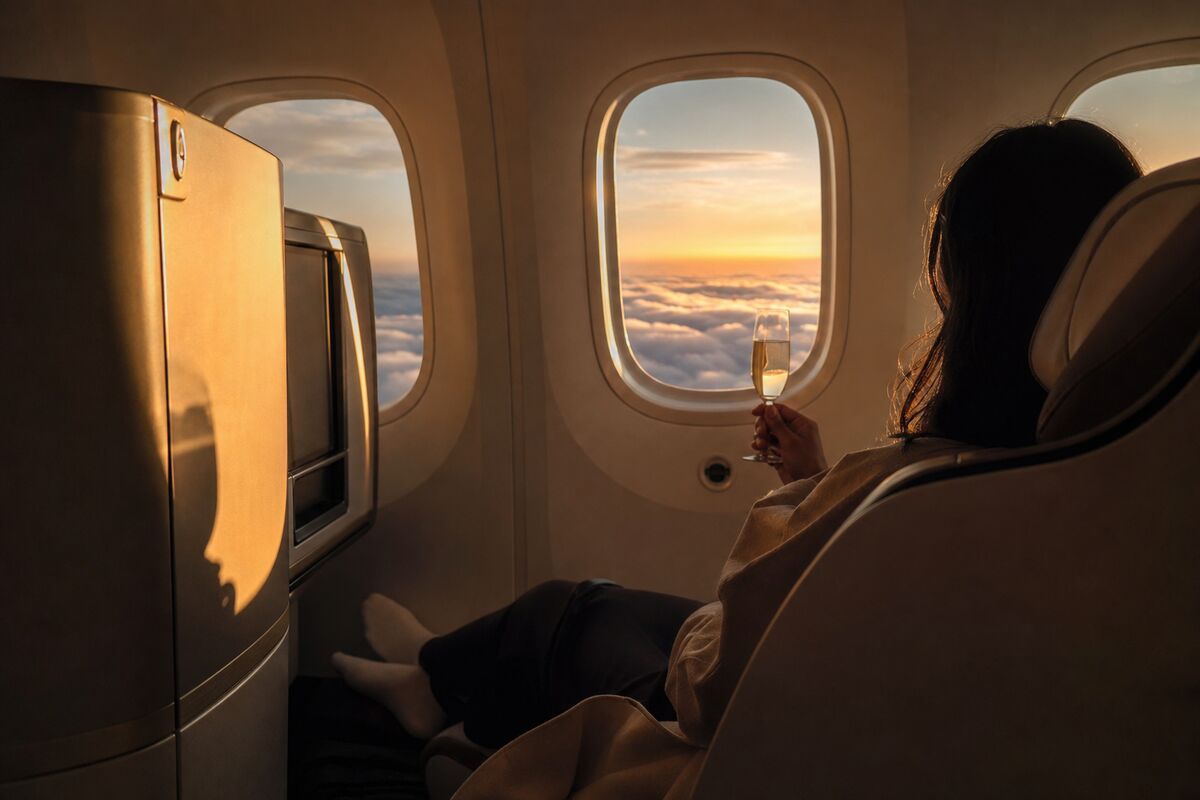
The central test is straightforward: can better onboard products attract a more valuable customer mix and strengthen JetBlue’s competitive position while high fuel costs and intense competition weigh on the airline industry? Management’s answer will become more tangible when JetBlue showcases its new first-class seats to reporters.
That product reveal matters because the strategy is not simply about adding a more comfortable seat. It is a bet on revenue quality. Premium offerings may help JetBlue appeal to travelers willing to pay more for an upgraded experience, potentially broadening the carrier’s customer base beyond the most price-sensitive segment.
For equity investors, the premium push offers a possible route toward stronger earnings. For creditors, however, the question is whether the strategy can translate into dependable cash generation quickly enough to address concerns about the company’s financial position. Those are related, but distinct, tests: shareholders may focus on the upside from a successful repositioning, while lenders and other creditors are more directly concerned with balance-sheet resilience and financing risk.
Why the premium bet matters
JetBlue’s approach reflects a difficult competitive reality. Low-cost carriers face pressure from elevated fuel costs, while the premium travel segment remains contested by larger airlines seeking to capture customers who prioritize comfort and service. JetBlue therefore needs its upgraded offering to do more than create publicity. It needs to support a clearer market identity.
The new first-class seats provide a visible symbol of that identity. They could help management demonstrate how JetBlue intends to differentiate itself, but the broader investment case will depend on execution. Product quality, customer demand and the ability to convert interest into sustainable revenue will matter more than the launch presentation alone.
In a CNBC report on JetBlue’s premium strategy, the CEO pushed back on creditor fears while emphasizing the role of premium offerings in the turnaround plan. That response puts management’s credibility at the center of the story. Investors will be watching whether confidence is matched by measurable progress, while creditors will be assessing whether the plan reduces—not merely reframes—financial pressure.
What investors should monitor
- Execution: Whether JetBlue can deliver the promised premium experience consistently across its operation.
- Demand: Whether travelers show sufficient willingness to choose and pay for upgraded service amid competitive pressure.
- Revenue mix: Whether premium offerings attract customers who improve the quality and durability of revenue.
- Financing: Whether balance-sheet concerns constrain the airline’s ability to carry out the strategy.
- Cost pressure: Whether high fuel costs undermine the benefits of a more premium positioning.
JetBlue’s turnaround is consequently a broader test of low-cost-carrier viability. A premium strategy may offer differentiation and a path toward positive earnings, but it also raises the stakes for execution and financing. The first-class-seat showcase will generate attention; the more important evidence will come from customer response and the company’s ability to sustain the plan under difficult industry conditions.
Bull/Bear Verdict
Bull Case: JetBlue’s new first-class seats and broader premium offering could improve its customer mix, strengthen competitive positioning and support a return to positive earnings if demand and execution are favorable.
Bear Case: High fuel costs, premium-segment competition and creditor concerns could limit the strategy’s impact if demand disappoints or financing pressure restricts execution.