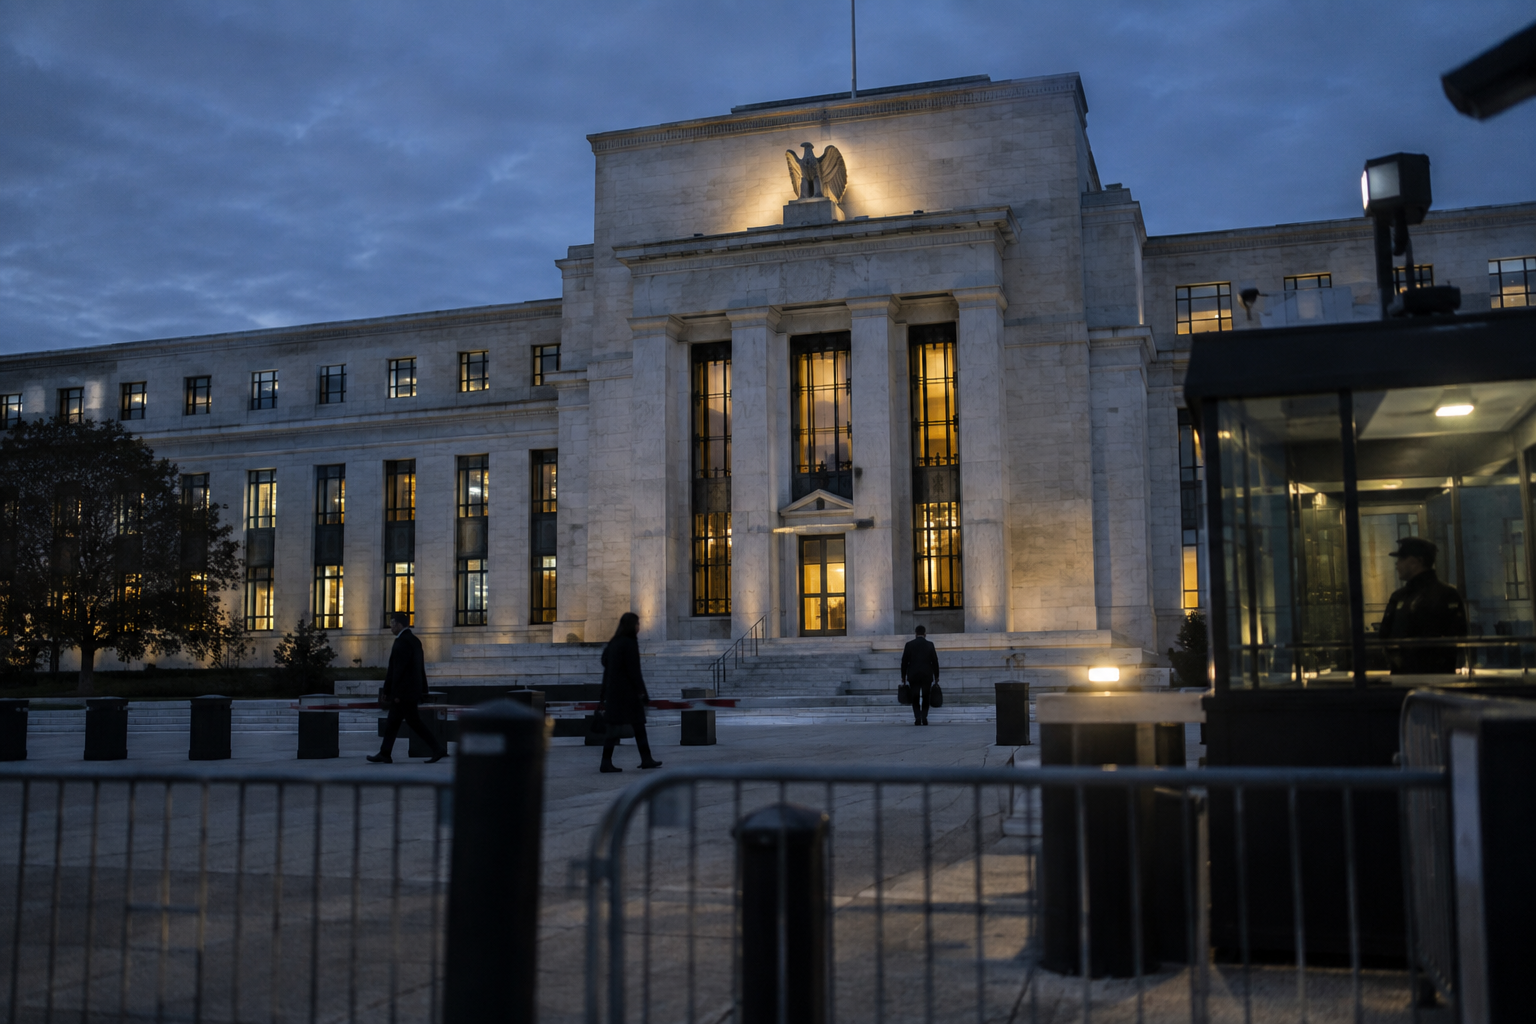
New York Fed President John Williams has delivered a clear challenge to traders expecting near-term rate relief: another Federal Reserve rate hike by year-end would be reasonable. The remarks arrive as the U.S. 10-year Treasury yield trades near 5.12%, its highest level since 2007, creating a sharper test for equity, bond and currency positioning.
Williams’ comments do not represent a confirmed policy decision, but they reinforce the possibility that the Federal Reserve may keep its policy stance restrictive for longer than markets had anticipated. For U.S. and Canadian traders, the signal matters because the 10-year yield is already operating at a level that can pressure growth-sensitive assets and reshape expectations across North American markets.
Speaking at the London Macro Policy Forum, Williams said another rate hike by year-end would be reasonable. The timing and setting matter: the comment comes against a backdrop of a 10-year Treasury yield near 5.12%, its highest level since 2007. That combination puts the Fed’s policy signal and the bond market’s repricing in the same frame.
A challenge to rate-relief expectations
Traders who had been anticipating easing now face a less supportive policy narrative. Williams’ statement suggests that the Federal Reserve’s discussion remains focused on whether additional restraint may be appropriate, rather than on the timing of rate relief.
That distinction is important. The comment is a policy signal, not a confirmed move. Still, it may encourage markets to assign greater weight to a higher-for-longer interest-rate outlook. When the 10-year yield is near 5.12%, expectations about future Fed decisions can have an amplified effect on bond pricing and equity valuations.
Why equities and bonds remain exposed
Higher yields can create pressure for growth and technology stocks because those areas are particularly sensitive to changes in the rate outlook. The assignment does not provide specific stock-price data, so the effect should be framed as a potential valuation and positioning pressure rather than a documented move in any individual company or index.
The same signal may also weigh on rate-sensitive assets more broadly. Bonds face continued pressure when investors demand higher yields, while equities may confront a less favorable discount-rate environment. For Canadian traders, the U.S. Treasury market remains a key external reference point even when the focus is on TSX-listed assets, because changes in U.S. rates can influence broader North American financial conditions.
The dollar signal
A higher-for-longer Fed outlook could support a stronger U.S. dollar by reinforcing the relative appeal of dollar-denominated assets. That possibility adds another layer to cross-border positioning for U.S. and Canadian market participants. However, Williams’ remarks alone do not establish a guaranteed currency outcome; they indicate how policy expectations could evolve if additional tightening becomes more likely.
The key message is therefore conditional. Williams is not announcing a rate hike. He is stating that another increase by year-end would be reasonable, at a moment when the 10-year yield is near 5.12%. That combination may keep traders focused on duration, growth exposure and currency sensitivity rather than positioning solely for imminent easing.
For the Federal Reserve and the New York Fed, the communication reinforces policy flexibility. For markets, it raises the cost of assuming that rate relief is close at hand. The next phase of trading may depend less on a single comment than on whether yields remain elevated and whether further Fed officials echo the same higher-for-longer message. Read the source report on Williams’ remarks and the Treasury-yield backdrop.
Bull/Bear Verdict
Bull Case: A higher-for-longer policy signal could support the U.S. dollar and reinforce confidence that the Federal Reserve is prepared to respond to persistent inflation pressure, while the 10-year yield near 5.12% gives markets a clear reference point for rates.
Bear Case: Another potentially reasonable rate hike, combined with a 10-year yield near its highest level since 2007, could extend pressure on growth and technology stocks, bonds and other rate-sensitive assets.