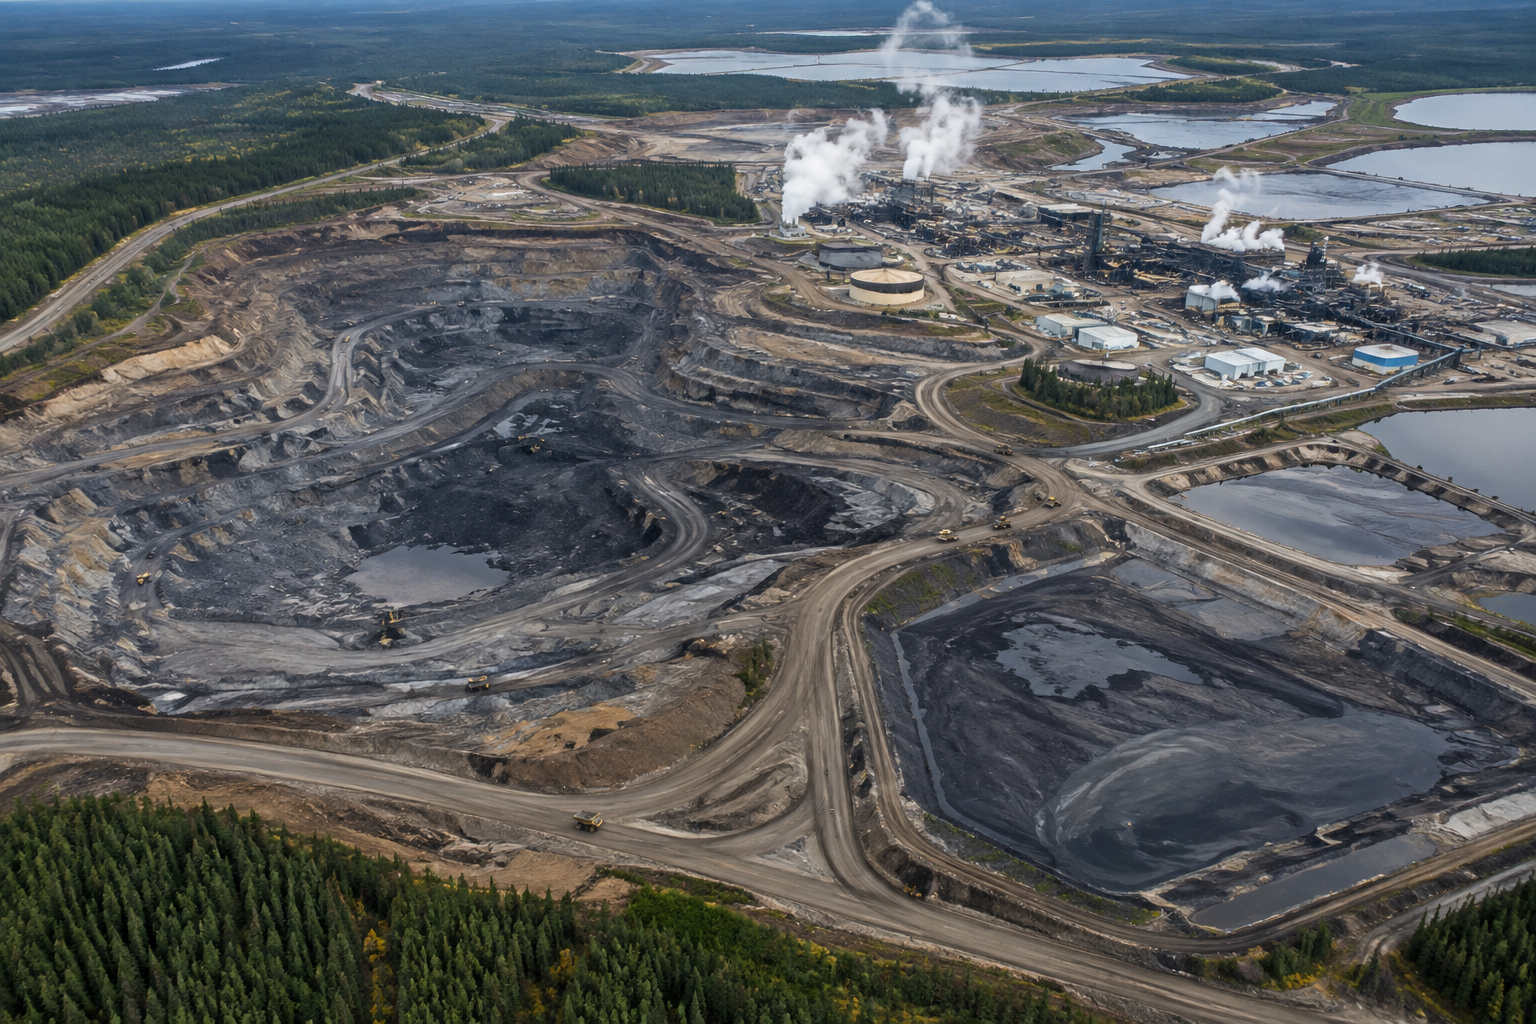
Canadian oil sands consolidation is no longer a theoretical theme—it has a transaction attached to it. Cenovus Energy Inc. (TSX: CVE, NYSE: CVE) has entered a definitive arrangement agreement to acquire Athabasca Oil Corporation (TSX: ATH) in a cash-and-stock transaction with an implied enterprise value of approximately $5.7 billion, according to Seeking Alpha coverage.
The immediate significance is straightforward: two Calgary-based Canadian oil producers are moving toward combination, consolidating oil sands production capacity under Cenovus. The broader significance is more important for markets. This deal could become a reference point for how investors assess other mid-cap Canadian energy companies—and it puts the strategic value of oil sands exposure back in focus.
A meaningful consolidation test for Canadian energy
Cenovus and Athabasca are both based in Calgary, Alberta, and both operate within Canada’s oil-producing landscape. The proposed transaction would bring Athabasca into a larger publicly traded platform, giving the Canadian energy sector a fresh example of consolidation involving oil sands assets.
That matters because the market often evaluates producers not only as individual companies, but also as potential pieces of a broader portfolio. A definitive agreement between two Canadian producers suggests that scale and asset combination remain central strategic considerations. It does not, by itself, establish that additional transactions will follow. But it gives investors a concrete deal against which future consolidation discussions may be measured.
The transaction is structured as cash and stock, and the implied enterprise value is approximately $5.7 billion. That figure, as reported in the supplied coverage, is the central valuation marker for this announcement. Investors should resist turning it into a universal multiple or sector-wide conclusion: the assignment provides no additional valuation metrics, and comparisons among producers would depend on asset mix, operating performance and transaction structure.
Why the valuation reference matters
For other TSX-listed mid-cap oil producers, the Athabasca agreement may establish a useful market reference. The approximately $5.7 billion enterprise value gives investors a transaction-scale data point when considering the strategic value assigned to a Canadian oil producer in a negotiated cash-and-stock deal.
That reference could influence how the market frames potential combinations, particularly among companies with meaningful oil sands exposure. It may also sharpen questions around whether standalone producers could command greater strategic relevance within a larger platform. Those are possibilities, not conclusions. The deal does not provide enough information to determine how the market will value every other Canadian producer.
Still, the signal is difficult to ignore. Consolidation can change how investors view a company’s assets, operating footprint and position within the Canadian energy industry. Cenovus’s agreement with Athabasca makes those questions more immediate for the TSX energy group.
A two-market story
The transaction is directly relevant to TSX investors because Cenovus and Athabasca are both Canadian-listed companies, while Athabasca trades on the TSX under $ATH and Cenovus trades under $CVE. The deal therefore sits squarely within the Canadian equity market and could become a focal point for investors tracking oil sands consolidation.
Cenovus’s NYSE listing broadens the audience. US investors seeking Canadian energy exposure can follow the acquiring company through its NYSE-listed shares under $CVE, rather than relying exclusively on the TSX. That does not change the transaction’s Canadian identity, but it does give the announcement a more direct connection to US-listed market participants.
For those investors, the key issue is not simply the headline value. It is whether the proposed combination changes the way the market views Cenovus’s scale and the strategic importance of Canadian oil sands assets. The agreement may encourage closer scrutiny of Canadian energy consolidation from both sides of the border.
The bottom line
Cenovus’s proposed acquisition of Athabasca is a substantial Canadian energy transaction, with an implied enterprise value of approximately $5.7 billion and a structure combining cash and stock. It consolidates oil sands production capacity, creates a fresh benchmark for discussions around mid-cap Canadian producers and gives US investors a clear connection through Cenovus’s NYSE listing.
The contrarian takeaway is that the market may be entering a phase where asset scale and strategic fit matter more than isolated company narratives. Whether this becomes the start of a broader wave remains uncertain. For now, however, the Cenovus-Athabasca agreement is a specific, measurable signal that Canadian oil sands consolidation deserves renewed attention.
Bull/Bear Verdict
Bull Case: The proposed cash-and-stock acquisition could strengthen Cenovus’s oil sands platform, while the approximately $5.7 billion enterprise value may provide a constructive valuation reference for other Canadian producers.
Bear Case: The transaction remains proposed, and the approximately $5.7 billion figure alone does not establish valuations for other TSX-listed producers or guarantee a broader consolidation wave.